Payback Period in Project Management: Formula + Template

The payback period in project management is how long an investment takes to return the cash you put in. Dividing one number by the other is the easy part.
Firms get it wrong on the inputs: what a tool or a hire cost, and when the cash cleared.
We cover what the payback period is and how to calculate it three ways. One $50,000 investment through the averaging, subtraction and discounted methods comes back at 3.57, 4.00 and 4.43 years. You also get benchmarks by investment type, the downsides, a template, and the four mistakes that break the number.
Key Takeaways
- The payback period is how long an investment returns cash, counted from collections not invoices.
- Two methods and one variant: averaging for steady returns, subtraction for uneven ones, discounted when timing matters.
- On one $50,000 investment they return 3.57, 4.00 and 4.43 years. The method you pick moves the answer ten months.
- The payback period screens investments, it never ranks them. Run it alongside a second metric before you commit budget in Productive’s project management platform.
What Is the Payback Period?
The payback period is the time required to recover an initial investment from the cash it generates. A shorter cost recovery window means you start earning sooner. It also means less exposure if the client or service line does not last.
The method has one structural weakness. It ignores the time value of money. Cash arriving in year four is worth less than the same amount today. The discounted payback period corrects for that.
Payback is also not the break-even point, and neither is a full investment appraisal. Break-even is about the order volume that clears your fixed and variable costs. The payback period is about one investment and one clock.
How to Calculate the Payback Period
You calculate the payback period with the averaging formula when returns are steady, or subtraction when they are not. Both need the same two inputs: what you spent, and what came back.
Initial investment / average annual cashflow = payback period
The arithmetic is not where firms go wrong. Your cash outlay is easy to underestimate. Your net cash flow is easy to overstate: the fee on the statement of work is not cash you keep. Most tools that track delivery cost per project exist for that gap.
In services, cash flow means collected revenue minus the cost of delivering it. A retainer billed net-30 pushes your recovery point out by the same lag you carry on receivables.
So both halves of the payback period formula have to come from the same records. If cost rates, logged hours and billed amounts sit apart, your initial investment and your return are guesses.
Productive’s budgeting and profitability ties logged time, cost rate and invoiced revenue to one budget.
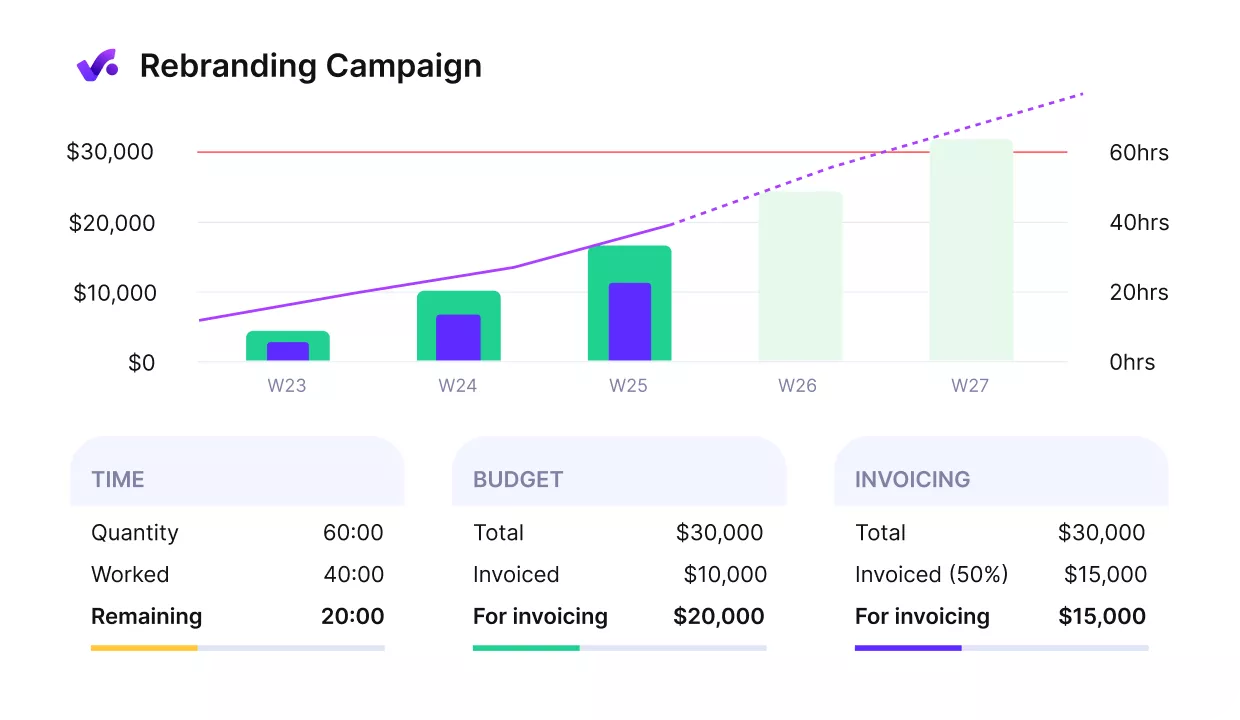
Get budget forecasts and warnings of overruns.
Payback Period Formula With Examples
The payback period formula comes in two forms: the averaging method when returns arrive at a steady pace, and the subtraction method when they do not. Each payback period example below uses the same $50,000.
How Do You Run the Averaging Method?
Run the averaging method by dividing the initial investment by the net cash it returns in an average year.
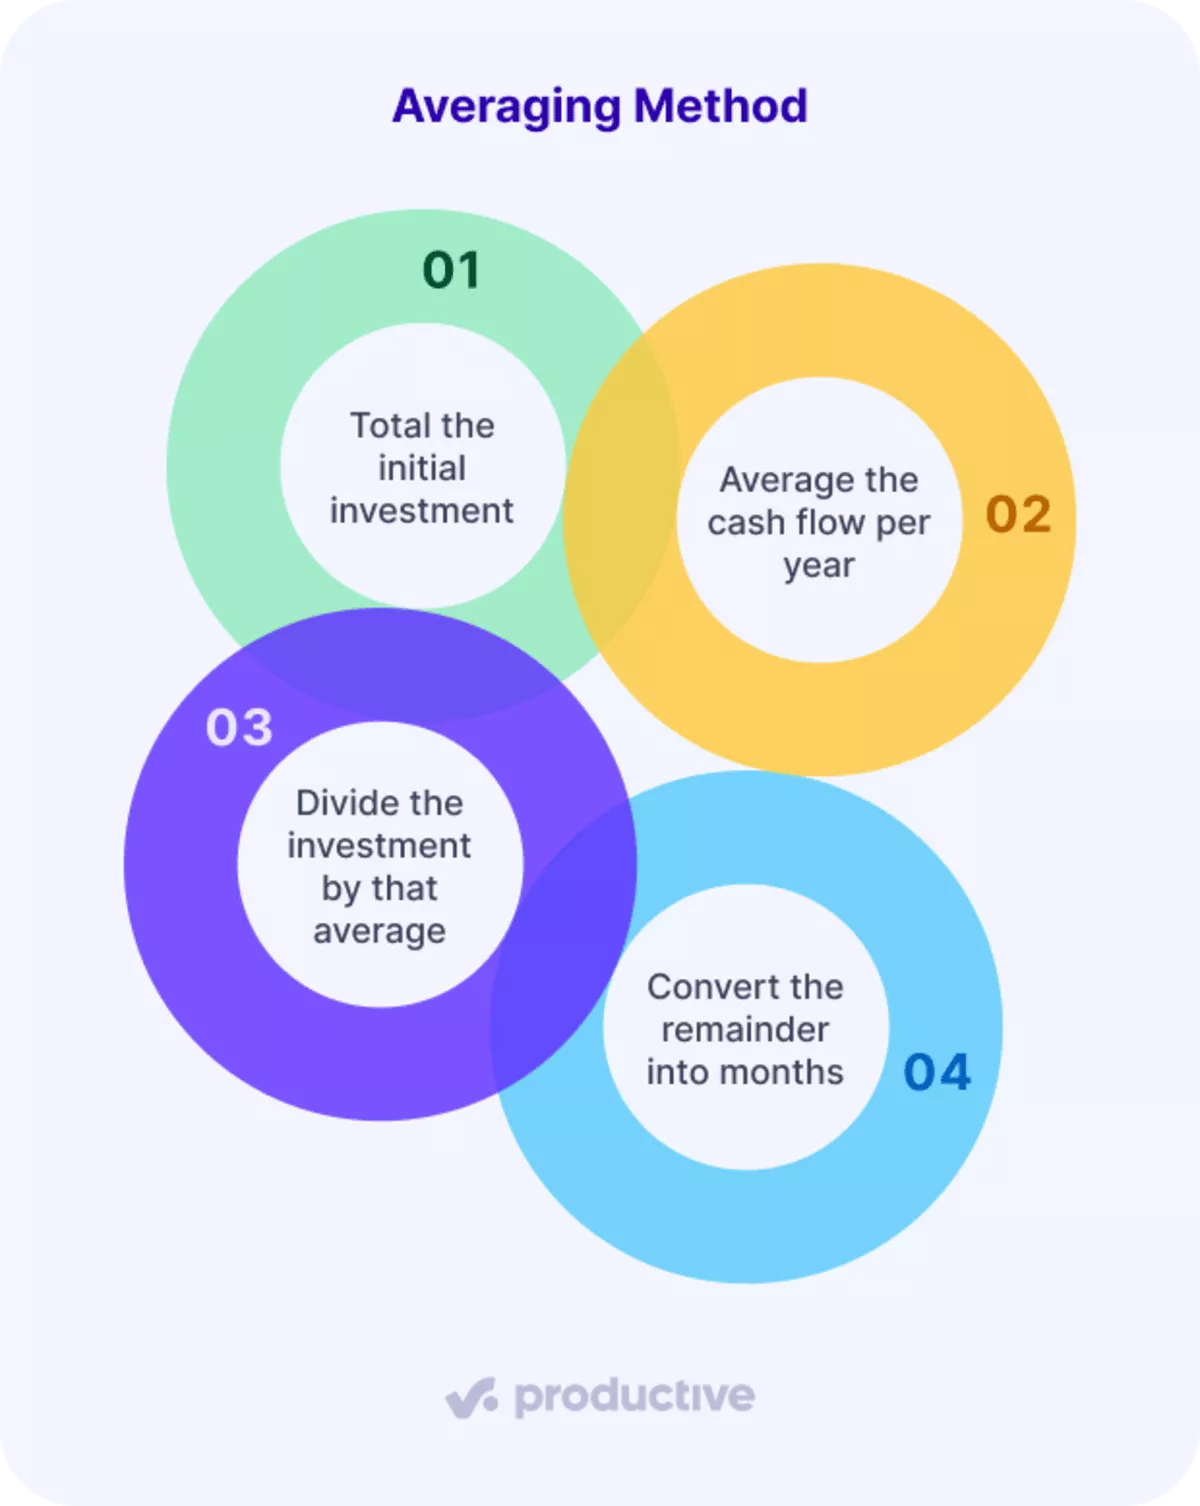
- Total the initial investment. Count every cost before returns start: licence fees, onboarding hours at cost rate, recruitment fees, non-billable ramp. Leave out any line you cannot trace to a source document.
- Average the cash flow per year. Take collected revenue minus delivery cost, one figure per year, then divide by the number of years. Use three years or more. Two years swings on a single late invoice.
- Divide the investment by that average. The result is the payback period in years. If it falls beyond the years you have figures for, switch to the subtraction method.
- Convert the remainder into months. Multiply the decimal by 12 and round to a whole month. Calculating payback period in months is what firms actually approve against.
Say you put $50,000 into a new service line. Cash inflows net of delivery cost arrive at $5,000, $10,000, $15,000, $20,000 and $20,000. Your cash flow per year averages $14,000 across those five years.
50,000 / 14,000 = 3.57 years
That reads as 3 years and 7 months. The averaging method appeals for one reason: a single division and a single number. What it hides is the shape of the return. Year one brought in $5,000, not $14,000, so real recovery comes later than this figure claims. Longer periods and steeper ramps widen the gap.
How Do You Run the Subtracting Method?
You run the subtracting method by drawing collected cash down against the investment until the balance hits zero. The subtraction method fits uneven returns.
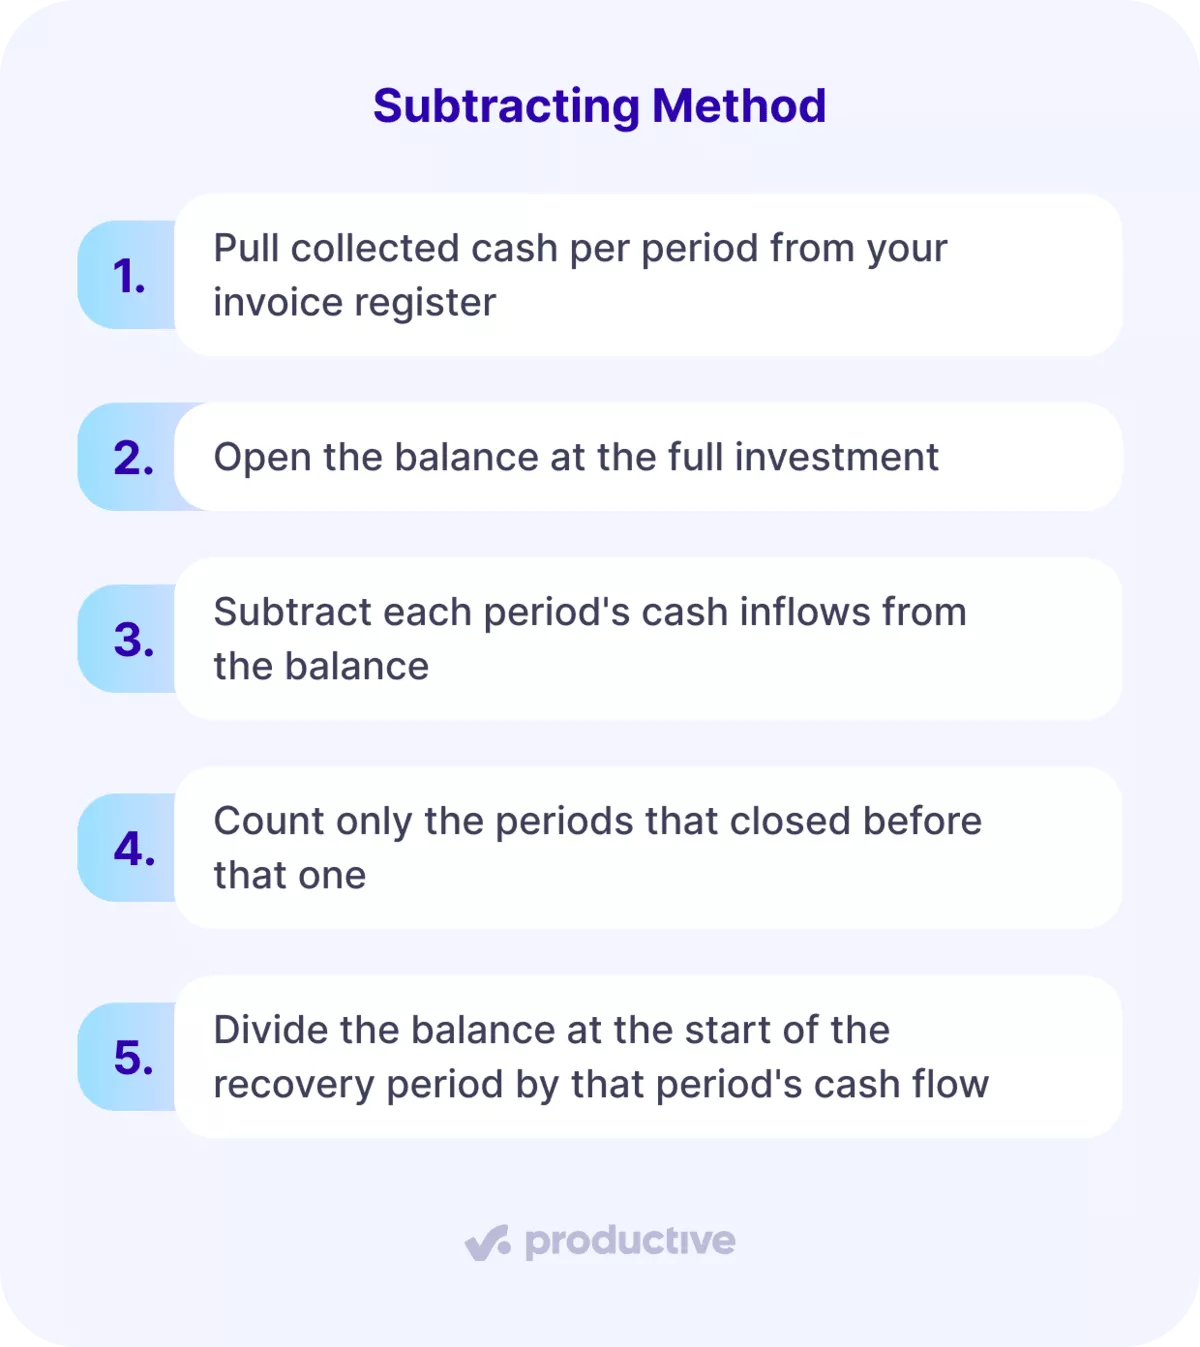
- Pull collected cash per period from your invoice register. One line per year, using amounts that cleared. If a period’s invoice is still in receivables, enter zero.
- Open the balance at the full investment. Period zero carries the entire cost, before any cash inflows arrive.
- Subtract each period’s cash inflows from the balance. Stop at the first period where it reaches zero or goes negative. Tracking cumulative cash inflows climbing toward the investment total gives the same answer.
- Count only the periods that closed before that one. Recovery inside year four means three closed periods, not four. This is where the calculation usually goes wrong.
- Divide the balance at the start of the recovery period by that period’s cash flow. Add the fraction to your count for the payback period. A fraction above 1.0 means you picked the wrong period.
Take the same $50,000 and the same inflows. Your running balance draws down like this:
| Year | Collected | Balance remaining |
|---|---|---|
| 0 | n/a | $50,000 |
| 1 | $5,000 | $45,000 |
| 2 | $10,000 | $35,000 |
| 3 | $15,000 | $20,000 |
| 4 | $20,000 | $0 |
Three years closed before recovery, and year four covers the remaining $20,000 exactly:
3 + (20,000/20,000) = 4 years
Count four closed periods instead of three and you get five, which is the trap. The averaging method put this investment at 3.57 years. The subtraction method puts the payback period at four, five months later, because the ramp back-loads the return.
How Do You Run Discounted Payback?
You run discounted payback by restating every future collection at present value before you draw it down. It answers what the first two methods ignore: $20,000 arriving in year five is worth less than $20,000 now.
That correction needs a discount rate, the annual rate that converts future cash into present value. It is how the time value of money enters the calculation.
Most firms use their cost of capital, or the return they would accept elsewhere. Pinning the cost of capital down precisely takes real financial analysis. A defensible estimate beats a stalled calculation, and it is the same discounting a DCF model runs.
Apply 5% to the same collections and every figure shrinks:
| Year | Collected | Present value at 5% | Balance remaining |
|---|---|---|---|
| 0 | n/a | n/a | $50,000 |
| 1 | $5,000 | $4,762 | $45,238 |
| 2 | $10,000 | $9,070 | $36,168 |
| 3 | $15,000 | $12,958 | $23,210 |
| 4 | $20,000 | $16,454 | $6,756 |
| 5 | $20,000 | $15,671 | recovered |
Year five clears the remaining $6,756 out of $15,671:
4 + (6,756/15,671) = 4.43 years
That reads as 4 years and 5 months, behind the undiscounted payback period of 3.57. One investment, three answers, and only the discounted payback period accounts for the time value of money. Discounted payback always runs longer where money arrives late, which in services is most projects.
A Template You Can Reuse
This is the payback period template. Copy it and run your own figures.
| Year | Collected | Discount factor | Present value | Cumulative cash flow | Balance remaining |
|---|---|---|---|---|---|
| 0 | n/a | n/a | n/a | 0 | investment |
| 1 | invoices cleared minus delivery cost | 1 / (1 + rate) | collected x factor | running total | investment minus cumulative |
Add one row per year, dividing again by (1 + rate) each time. The discount factor is the only column with a formula, and at 5% in year three it is 0.8638. Your payback period is the last positive year, plus that balance divided by the next present value.
What Counts as the Initial Investment for a Services Firm?
For a services firm, the initial investment is every cost you carry before the work returns cash. Four get missed:
- Licence and implementation fees. The obvious entry, usually the smallest.
- Onboarding hours at cost rate. Ten people losing four hours each adds 40 hours to the initial investment.
- Recruitment and ramp for a hire. Your cost of acquisition covers every week before billing.
- Pre-sales effort on a new service line. Pitches, proposals and discovery calls are customer acquisition costs already spent.
Firms count the licence as the whole initial investment, because that line has an invoice against it. The other three are capital costs too. Leave out any cost of acquisition and the payback period you approve against comes back short.
What’s a Benchmark for a Good Payback Period?
A good payback period for a services firm is one to three years. Capital projects often quote three to five. The reason is exposure: the sooner an investment recovers, the sooner cash frees up.
Each investment type ramps differently. Set a target payback period per line item, not one figure for the firm.
- Retainer or engagement setup cost: three to six months, because onboarding effort should be earned back inside the first few billing cycles.
- A PSA or project tool: twelve to eighteen months, since the return arrives as reclaimed admin time rather than new revenue.
- A billable hire or new service line: twelve to twenty-four months, given the ramp before utilization and revenue settle.
Treat those as an expectation you set, not a published standard. Write the payback period down as a decision rule. Productive’s Scenario Builder models a range before you commit.
None of it holds if the inputs are guesses. Feed it logged hours at each role’s cost rate, the bill rate after write-offs, and the real invoice-to-payment lag.
What Are the Benefits of Using the Payback Period?
The benefits of using the payback period are speed and a single number everyone understands. It works as a first screen.
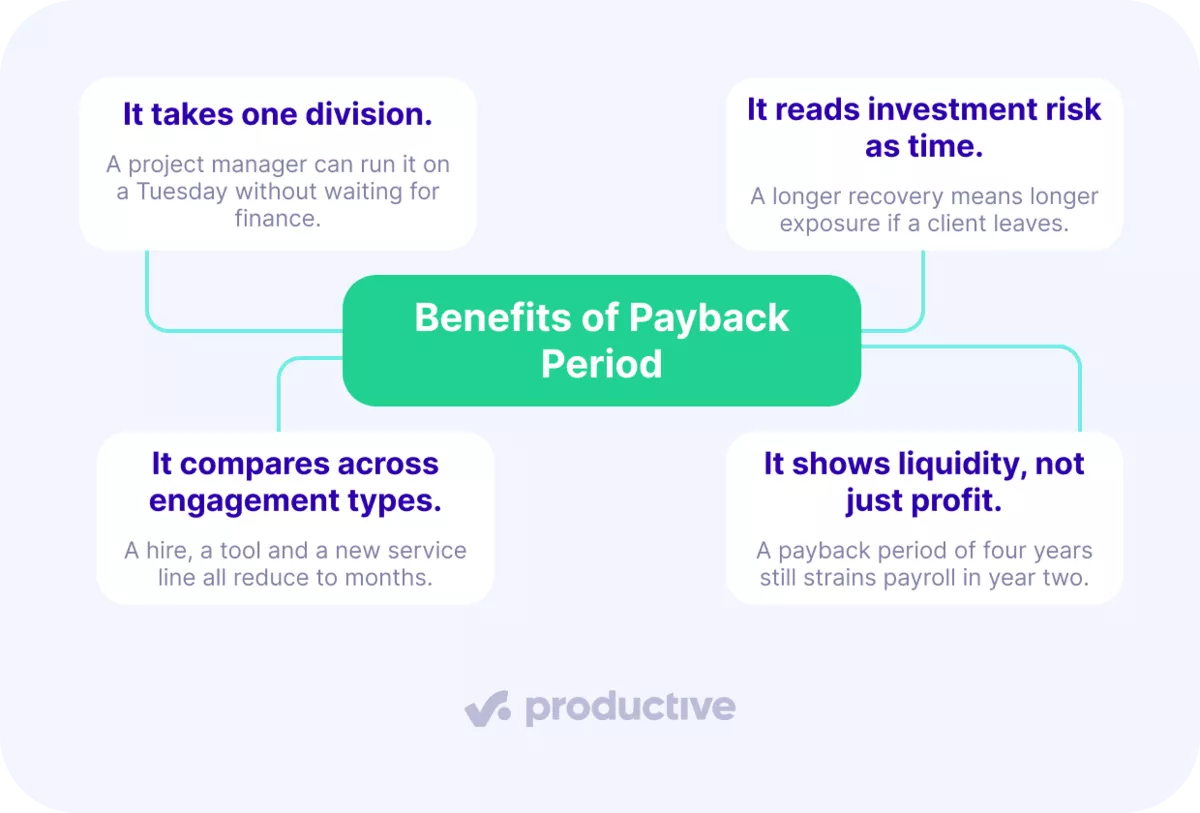
The financial benefits are narrow but real:
- It takes one division. A project manager can run it on a Tuesday without waiting for finance.
- It reads investment risk as time. A longer recovery means longer exposure if a client leaves.
- It compares across engagement types. A hire, a tool and a new service line all reduce to months.
- It shows liquidity, not just profit. A payback period of four years still strains payroll in year two.
Those financial benefits stop at the recovery date.
Where Does the Payback Period Fall Short?
The payback period falls short because it ignores the time value of money and stops measuring at recovery. It tells you how fast a project pays back, not what it earns after.
That gap bites hardest on the decisions services firms actually weigh. A retainer recouping cost in eight months can beat a service line recovering in six on long-term profitability.
- It rewards the shortest recovery, not the most profitable engagement. A fast-paying build can crowd out a retainer running at 45 percent margin.
- The basic formula assumes even cash flows, which rarely holds when billable revenue is lumpy.
- Results can disagree with NPV or IRR. A senior day rate booked in year three counts for less than one billed this quarter.
- Used alone the payback period says nothing about long-term profitability, and hides utilization after the ramp.
Two of those are fixable in the calculation. The rest need other project management metrics worth tracking. Strategic fit is not something a recovery date tells you.
What’s the Difference Between the Payback Period and Alternative Financial Metrics?
The difference between the payback period and alternative financial metrics is speed against size. Payback measures how fast you recover a cost. Every other financial metric measures earnings.
| Metric | What it answers | When to reach for it | What it misses |
|---|---|---|---|
| Payback period | When the cash comes back | Screening a shortlist fast | Everything after recovery |
| Discounted payback | When does it come back in present value terms | Recovery beyond two years | Everything after recovery |
| Net present value | What is it worth in total | Choosing between different lifespans | Scale relative to cost |
| Internal rate of return | What annual return does it earn | Comparing investments of different sizes | Multiple answers on odd cash flows |
| Return on investment | What percentage did it return | A simple after-the-fact read on calculating the return a project delivers | Timing entirely |
| Break-even | What volume covers costs | Pricing a service line | The investment itself |
Capital budgeting works as a financial strategy: payback screens, another metric decides. Investment appraisal on one metric picks wrong, confidently.
Payback Period vs Net Present Value
The payback period tells you when your cash returns. Net present value tells you what the investment is worth. The payback period tells you when your cash comes back. Reach for net present value when strategic fit points at a multi-year retainer over a fixed-fee build. Only one keeps earning.
Payback Period vs Internal Rate of Return
The payback period gives you a date. Internal rate of return gives you an annual percentage across the project life. Reach for internal rate of return when comparing a $20,000 hire against a $200,000 platform. A percentage compares across sizes. A recovery date does not, which is how IRR values a full project life differently.
Payback Period vs Break-Even Analysis
The payback period asks how long recovering one investment takes; break-even analysis asks what order volume covers your costs. Reach for break-even analysis when pricing a new service line. The break-even point gives you billable hours per month. That break-even point moves every time your cost rates do.
How Do You Rank Investments by Payback Period?
You rank investments by payback period by screening first and ordering second. Drop anything recovering slower than your benchmark, then order what is left by total return. The fastest recovery is rarely the best return.
Take two project proposals at $50,000 each. The first is a fixed-fee build collecting $30,000, $20,000 and $10,000. The second is the retainer above.
| Fixed-fee build | Retainer | |
|---|---|---|
| Payback period | 2.0 years | 4.0 years |
| Collected over five years | $60,000 | $70,000 |
| When the cash arrives | first two years | years three to five |
The build recovers twice as fast and returns $10,000 less. Payback period is a screen, not a verdict.
So write your decision rule down. Project selection comes down to two ordered questions: does it recover inside your benchmark, and does it beat the alternatives on total return or cost-benefit ratio.
Investment decisions made on payback alone favour short, thin work. Project selection by speed is a financial strategy nobody chose. A deliberate financial strategy ranks on what the money earns.
Project selection needs live inputs. tools that model future cash flow keep collection figures current rather than frozen at kickoff.
Productive turns your resource schedule into projected revenue and margin, then re-ranks your project proposals as bookings change.
Why Does Your Payback Estimate Slip After Kickoff?
Your payback period estimate slips because spend only becomes visible after the work is logged and reconciled. By the time a designer books ten hours against an eight-hour estimate, those hours are gone.
The kickoff number assumed a blended rate of $120 an hour at 75 percent utilization. If seniors absorb junior tasks, real cost per delivered hour climbs. The recovery point moves out a quarter and nobody updates the figure.
Real-time burn tracking closes that gap by comparing logged hours against the estimate as work happens. Productive shows burn against each budget as time is tracked, and custom alerts fire before a budget is spent.
Tools that flag budget burn early work on that principle.
Reconcile logged cost against the fixed-fee ceiling weekly. A 40 percent burn at the 25 percent milestone should trigger a scope conversation, then a corrected payback figure.
Brigada reviews its project phases every six months, and how Brigada repriced its unprofitable phases shows what that surfaces. Before the cadence existed, the agency had no accurate profitability read until a project was delivered.
How Do You Keep Your Payback Inputs Accurate?
Keep your payback period inputs accurate by linking tracked hours to the budget they bill against. The invoice then draws from logged time, not a hand-built summary.
That connection is what makes cash flow management possible mid-project. In Productive, approved hours generate the invoice with no separate consolidation step. Forecasting from your resource schedule then projects revenue and margin from the same record. Your financial analysis then runs on what a project manager actually booked.
Two things break that chain more than anything else.
What Does the Manual Monthly Pass Cost You?
The manual monthly pass costs you senior billable hours, and it quietly breaks the payback period math. A project manager cross-checking timesheets against draft invoices two days a month books 16 non-billable hours. Over a four-year recovery that is 768 hours at a fully loaded rate, invisible in the formula.
What Slips Through When Records Don’t Match?
When records don’t match, what slips through is billable time logged against the wrong code. Or time entered after the invoicing cutoff. Those hours understate what the engagement earned. A project that looks recovered on schedule may still be leaking revenue you never captured. One consultant misallocating six hours a week across two accounts inflates one margin while starving the other.
What Are the Common Payback Period Mistakes?
The common payback period mistakes are forecast revenue, unpriced ramp, gross fee as cash flow, and a stale figure. Each one flatters the number:
- Using forecast revenue instead of collected. The invoice you sent is not cash you have.
- Ignoring non-billable ramp. A project manager onboarding a team burns capacity that never reaches the total.
- Treating the gross fee as cash flow. Cash flow is fee minus the cost of delivery.
- Never revisiting the number. Market conditions and rates move, so a kickoff estimate is stale by the second review.
Re-run the financial analysis every six months. A project manager who reprices in month seven can still update the payback period.
Final Thoughts
A payback period is only as honest as the two numbers behind it: what the work cost to deliver, and when the cash cleared. Pull both from your records and project selection stops being guesswork.
Centralized tools keep your numbers, scenarios and forecasts in a single place. Book a short demo with Productive and start today.
Frequently Asked Questions
What does a short payback period tell you?
A short payback period tells you your cash is committed for less time. It says nothing about total profit.
Is the payback period the same as break-even?
No, the payback period is not the same as break-even. Break-even is the order volume that clears your costs.
When should you use simple payback instead of discounted?
Use the simple payback period method as a first screen. Past two years, discounting changes the answer enough to matter.
Does payback period analysis reject a long recovery?
Payback period analysis does not reject a long recovery on its own. A retainer recovering in four years and earning for six beats a build recovering in two.
What is payback period analysis missing?
Payback period analysis stops measuring at recovery. Pair the payback period calculation with net present value or internal rate of return.
Manage Budgets and Profitability With Productive
Switch from multiple tools and spreadsheets to an all-in-one solution for project, financial, and resource management.
